Often used for
- Owners choosing among 7(a), 504 and Microloan routes
- R&D companies checking SBIR or STTR
- Established exporters checking state STEP support
Check closely
- SBA loans must be repaid
- General startup grants are not an SBA program
- State and agency eligibility rules
- Registration and proposal lead time
Start with the business need
Define the amount, date required, use of funds and expected cash return. Those four facts narrow the product set before any lender markets an offer.
Compare like with like
For sba loans and business grants, put cash received, total repayment, term, payment frequency, fees, security and early-pay treatment into one table. The lowest advertised rate is not useful when products use different cost formats.
Check the downside
Model the payment against a weak month and include existing debt, payroll and tax obligations. Financing should bridge or fund a defined business outcome, not hide a recurring operating loss.
Find the SBA or grant route worth checking first
This is a program screen, not an approval or eligibility decision.
SBA 7(a) Working Capital Pilot
Monitored revolving credit for businesses with receivables, inventory, contracts or project-level working-capital needs.
- Rule to check
- Designed for businesses with at least one year of operations and timely financial, receivables, payables and inventory reporting.
- Next action
- Build current receivables and payables aging reports and ask the lender whether WCP or another CAPLines structure fits.
SBA 7(a)
Broad lender-made financing for eligible working capital, ownership changes, equipment, refinancing and real estate.
- Rule to check
- Repayment ability and lender underwriting still apply. The published program maximum is $5 million.
- Next action
- Prepare a use-of-funds schedule, debt list and three-year projection, then contact participating lenders.
SBA Microloan
Community-intermediary loans up to $50,000 for startup or expansion costs such as inventory, supplies and equipment.
- Rule to check
- Cannot be used to purchase real estate or pay existing debt. The intermediary sets its own credit rules.
- Next action
- Find a local intermediary and ask about training, collateral and personal-guarantee requirements before assembling the file.
USDA rural business route
Lender guarantees and rural-development programs for eligible projects in qualifying rural locations.
- Rule to check
- The project address, population test, borrower type and program-specific use decide eligibility before pricing begins.
- Next action
- Check the property address with USDA Rural Development and ask the state office which borrower-facing program is open.
Grant reality: SBA does not provide general grants to start or expand an ordinary business. Its direct small-business grant paths are narrow, including competitive R&D programs, while STEP assistance is delivered through states and territories.
Live funding benchmarks
Request-driven refresh every 6 hours, with dated fallbacks when a source cannot be reached.
60%Applied for financing
42%Received all financing sought
57%Small-bank full approval
60%Online borrowers reporting higher cost than expected
Program ceilings are calculated from the latest prime observation and SBA's published variable-rate margins, not a lender quote. SBA loan-level dataset shown as of 2026-03-31; catalog checked 2026-07-08. Rate source ↗ SOFR ↗ SBA rules ↗ SBA data ↗ Credit survey ↗
Loan, grant or technical assistance?
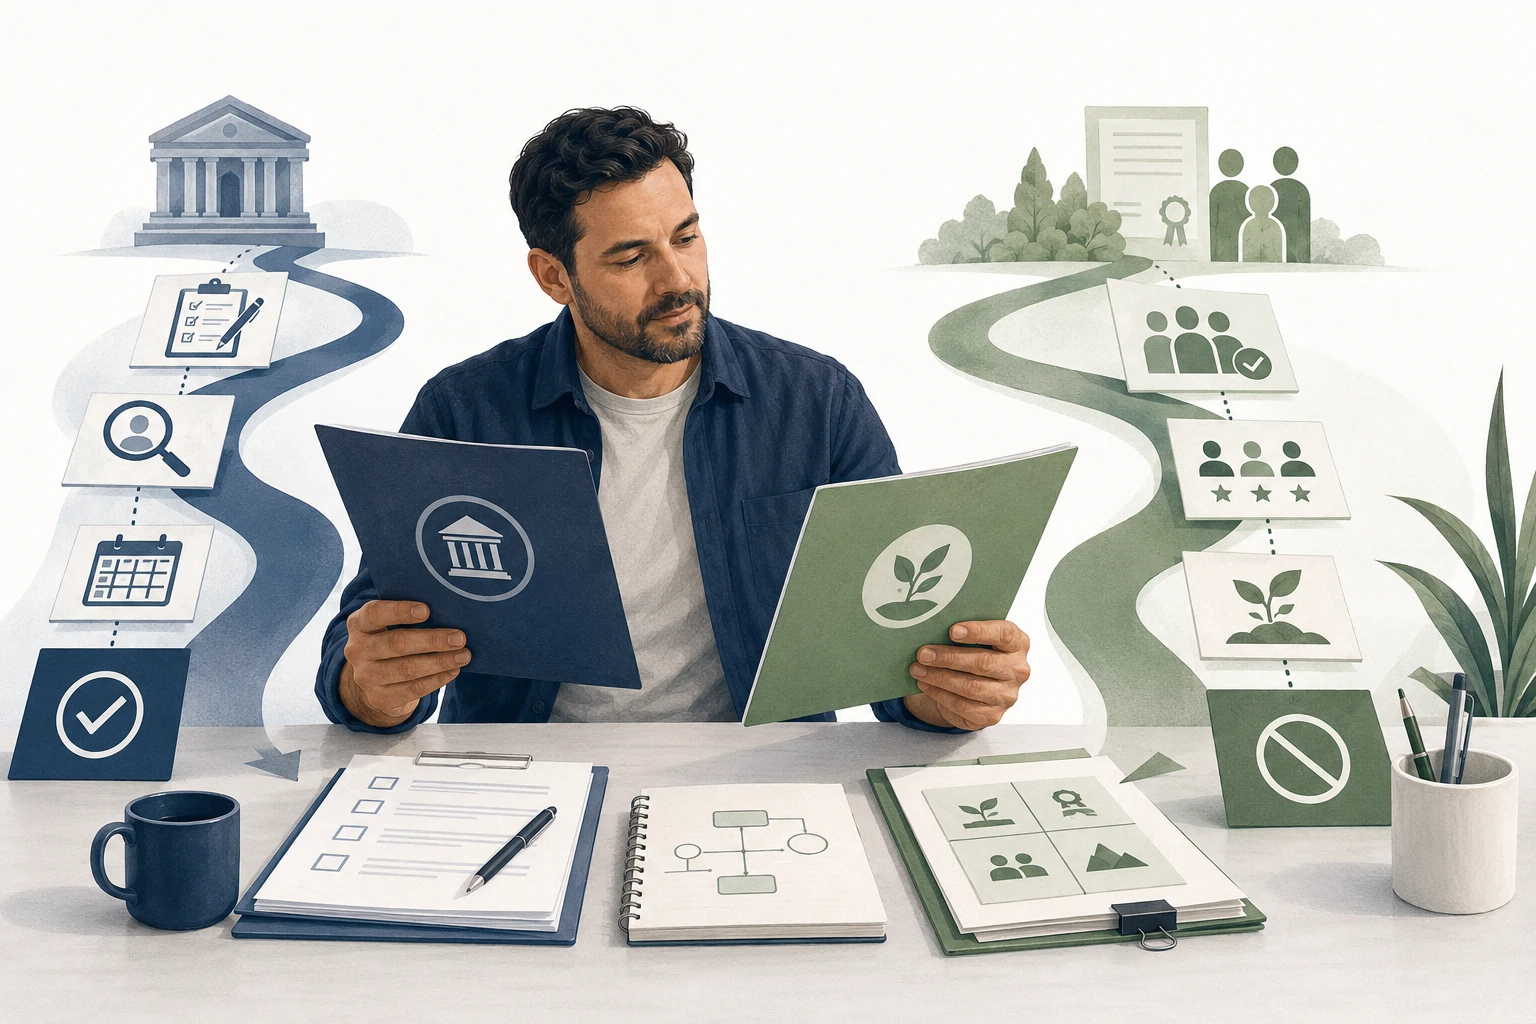
An SBA guarantee helps a participating lender make a loan. It does not cancel the borrower's obligation. A 7(a), 504 or Microloan has to be repaid under the signed agreement, and owners may have to guarantee the debt. The most useful first screen is the purpose of the money. Working capital and a business acquisition can fit 7(a). An owner-occupied property or long-life machine belongs beside 504. A request below $50,000 may fit a nonprofit Microloan intermediary.
Grants start from a different question: does the proposed work advance a specific public program? The SBA says it does not provide general grants to start or expand an ordinary business. Federal small-business awards exist for narrow purposes. SBIR and STTR fund agency-defined research and development. STEP money reaches small exporters through states and territories. A salon, restaurant or local service company should not write a generic grant proposal and hope the word small business is enough.
A seven-day SBA preparation sprint
Name the transaction
Write the amount, use, project address and date required. Separate working capital from property and equipment.
Map ownership
List every direct and indirect owner. Check current SBA citizenship, residency, affiliation and size rules before paying an adviser.
Reconcile the numbers
Make tax returns, bank deposits and current statements tell one story. Explain transfers and unusual receipts.
Build debt service
Add the proposed payment to every existing obligation and test the weakest month, not the annual average.
Document the use
Collect purchase agreements, quotes, invoices, a project budget or an acquisition file that supports each dollar.
Contact the right desks
Approach several participating lenders or a local intermediary with the same file and ask for the exact program route.
How to use the grant search without wasting a month
Start at the eligibility paragraph, not the award amount. Confirm that a for-profit small business can apply directly. Then check the technical topic, place of performance, ownership, employee limit, registration and submission date. Grants.gov tells applicants to read the attached opportunity instructions because the awarding agency defines legal eligibility there. A perfect narrative cannot cure an ineligible applicant.
For SBIR and STTR, match a real research task to an open agency solicitation. A normal website build, franchise purchase or marketing campaign is not research merely because it uses technology. For STEP, contact the selected state before spending money. States decide which activities, reimbursements, matching funds and application periods apply locally. Keep written approval and receipts for every reimbursable cost.
Official program references
SBA 7(a) ↗SBA 504 ↗SBA Microloans ↗SBA grants overview ↗SBIR and STTR eligibility ↗STEP ↗Grants.gov eligibility ↗
Program rules and open solicitations can change. These links were checked July 17, 2026.Loan versus grant
A small manufacturer needs $300,000 for equipment and $80,000 for experimental materials tied to an agency research topic.
Equipment routeSBA 7(a) or 504 screen
Research routeOpen SBIR or STTR topic
Ordinary marketingNot a federal R&D grant use
Run the math. The owner separates the commercial asset purchase from eligible technical research. Each dollar follows the rules of its own program.
Decision. Do not wait for an uncertain grant to close an equipment purchase. Submit only when the research task and applicant satisfy the solicitation's legal eligibility.
Start with the legal structure
SBA loans and business grants should be classified by its legal agreement, not its marketing label. An eligibility-first guide to SBA 7(a), 504 and Microloans plus the narrow federal grant routes that can serve research, exporting and specific public priorities.
Marketing categories often mix the use of funds with the contract. Working capital describes what the money does. A term loan, revolving line, lease or receivables purchase describes the obligation. Keeping those labels separate stops a fast sales pitch from turning unlike products into one rate table.
Put price on one clock
Compare net cash, total repayment, fees and time on one worksheet.
A useful example starts with a real amount, a real term and the weakest likely month rather than a lender maximum. The example is not a market quote. It shows the arithmetic an owner should run with the actual amount, payment dates and fees from a written offer.
Repayment and security
Match each payment date to the cash event expected to support it. Read guarantees, liens, collateral and default rights before accepting.
Run the proposed schedule through a low-revenue month. Keep taxes, payroll, rent, suppliers and existing debt in the forecast. If the business needs another advance merely to carry the new payment, the amount or product is wrong.
A five-column comparison before applying
Decision rule
Use the product only when the repayment source is specific and documented.
Before submitting bank data, write down the amount required, date needed, expected cash return and maximum safe payment. Those four facts will eliminate more poor offers than a long list of advertised lender limits.
Documents and questions that change the answer
Program eligibility should be checked before a full lender application. Ownership, citizenship, project address, use of funds and business size can decide the route before credit pricing begins. Keep the official program page beside the lender's checklist, because a participating institution can add underwriting rules without removing the federal or community-program rules underneath it.
Document timing is part of the cost. Tax returns, interim financials, ownership records and purchase documents can take days to assemble, while valuations or environmental work can take longer. Build the file against the real closing date. If the business needs cash sooner, compare a temporary facility separately and do not assume it can always be refinanced into the preferred program later.
Keep the first comparison small enough to read. Three written offers are more useful than ten callbacks with missing figures. Reject any result that will not identify the provider, total obligation or payment schedule before acceptance, then spend the saved time checking the agreements that remain.